Moving denominators! – Adjusting for hidden noise in inter-country comps
Minerva Asset Advisors | SEBI Registered Investment Adviser: INA000020332
Re-basing is required!
Our view remains unaltered on how poorly India stands on absolute value. Accordingly, for an allocator that isn’t hobbled by capital controls, in our view, India needs to make a compelling relative value argument for 1. Attracting capital, and 2. Retaining it. While headline multiples are casually tossed around for relative benchmarking, few comparisons are really as noisy as inter-country index comparisons. These get incrementally noisier when we compare benchmarks with high component attrition and/or meaningful underlying divergence between winners and losers. Effectively, stacking such benchmarks against themselves from years ago, or against others, needlessly attracts misplaced interpretations that are then used as planks to push through misplaced narratives.
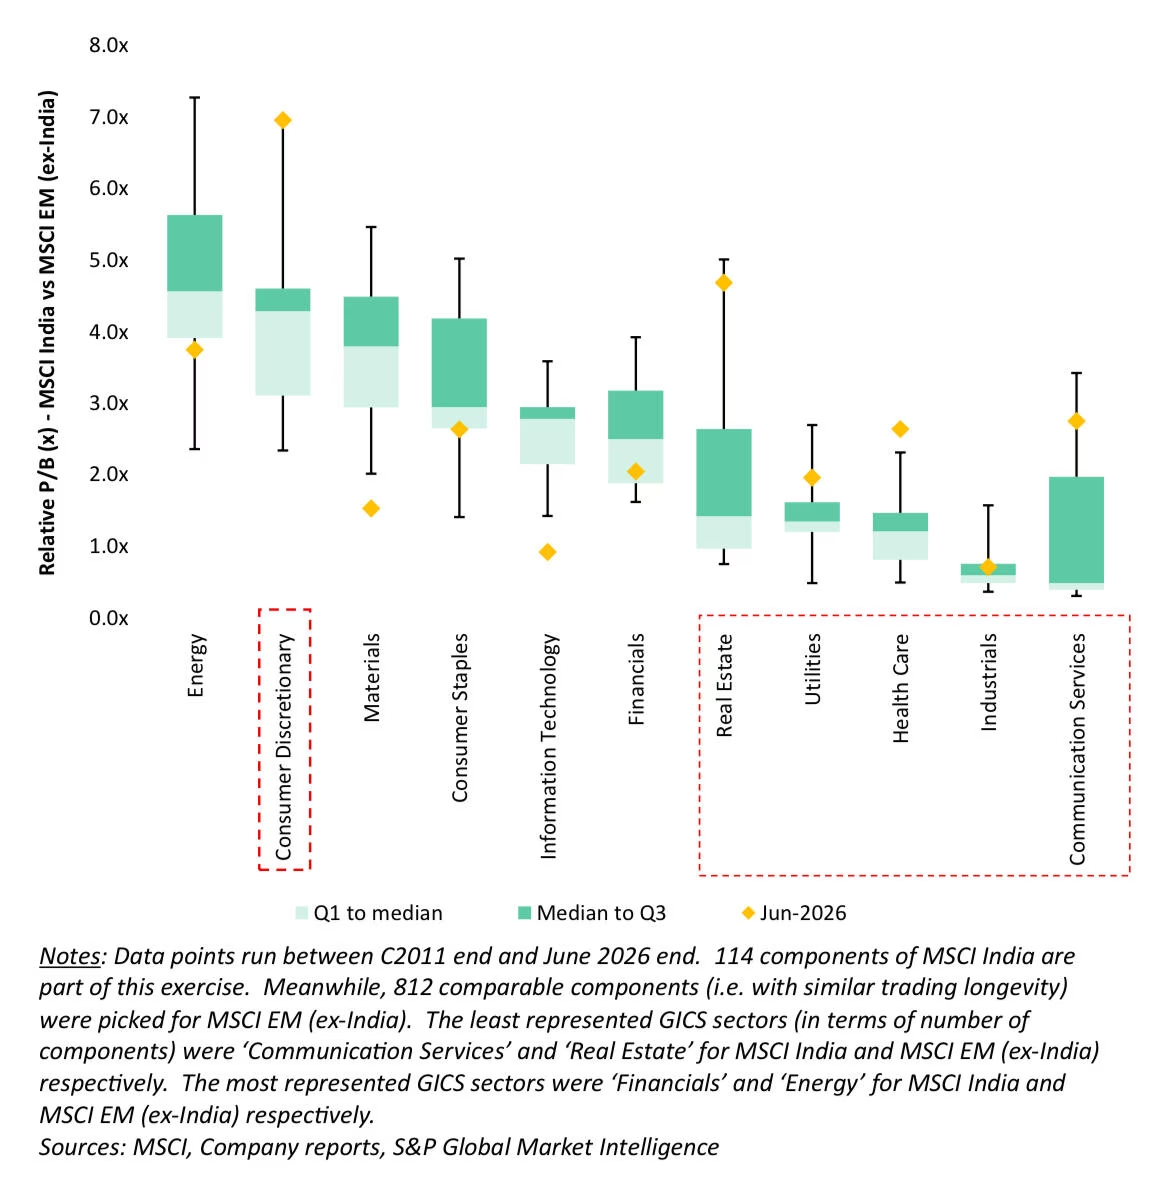
Around the beginning of last decade, Energy, Materials, Financials, and Utilities (let’s say intrinsically ‘low-multiple’ sectors) made around 58% of MSCI EM, vs. 51% for MSCI India. Contrast that with today - composition of the same 4 has since marginally ticked up within MSCI India while it has nearly halved at MSCI EM (and more than halved if we were to exclude India from MSCI EM). From the context of evaluating relative attractiveness today, it’s therefore outlandish to evaluate how these benchmarks have correlated historically. Instead, a cleaner relative value read-through can only be had by comparing sectors with themselves and without altering weights of sectoral components historically (i.e. by using current weights). That is exactly what the boxplot in the below exhibit does. The sector-wise dispersion of relative Price-to-Book for MSCI India vs. MSCI EM (excluding its Indian components) is plotted out. We only included names that have traded since at least C2011. What stood out?
1. Relative to MSCI EM, 6 of the 11 Indian GICS sectors (highlighted in ‘red’ dotted lines in the exhibit) began this quarter trading at levels that were still in the top-quartile of their history, and
2. If one were to exclude the steroidal post-pandemic binge, only 3 of 11 Indian GICS sectors now trade below historical averages, and mostly deservedly so. Why? - Be it emergence of coding assistance tools or continued internalization of development within Fortune 500 clients, Indian software names aren’t exactly dealing with temporal headwinds. These challenges cannot be wished away. Elsewhere, Indian staples names are simply trading at less ridiculous levels than where they used to – Less expensive than ‘absurd’ is still ‘expensive’.
DISCLAIMER: Investments in securities are subject to market risks. Read all the related documents carefully before investing. The information contained herein is believed to be reliable and has been obtained from sources believed to be reliable, but we make no representation or warranty, either expressed or implied, as to the accuracy, completeness or reliability of such information. We do not undertake, and have no duty, to advise you as to any information that comes to our attention after the date of this note or any changes in its opinion, estimates or projections. Prices and availability of securities are also subject to change without notice. This is not a prospectus and does not constitute investment advice or an offer or solicitation to buy or sell any designated investments discussed herein. Neither Minerva Asset Advisors, nor its officers, directors, agents, or employees make any warranty, express or implied, as to the suitability of any fund as an investment or of any kind whatsoever, or assumes any responsibility for, and none of these parties shall be liable for, any losses, damages, costs, or expenses, of any kind or description, arising out of this note or your investment in any fund. You understand that you are solely responsible for reviewing any fund, its offering and any statements made by a fund or its manager and for performing such due diligence as you may deem appropriate, including consulting your own legal and tax advisers. Minerva Asset Advisors | SEBI Registered Investment Adviser: INA000020332. Minerva India Under-served Fund LEI - 549300BQY3OUZWXLDZ68.