No two top-decile badges are the same
Minerva Asset Advisors | SEBI Registered Investment Adviser: INA000020332
Not all heavy hitting is associated with great stock picking
While ‘top of the class’ badges are widely trumpeted on the street, no two badges from two separate periods are the same. Skill and good fortune often wear the same suit in investing. Strip away the bull market and see who is still dressed.
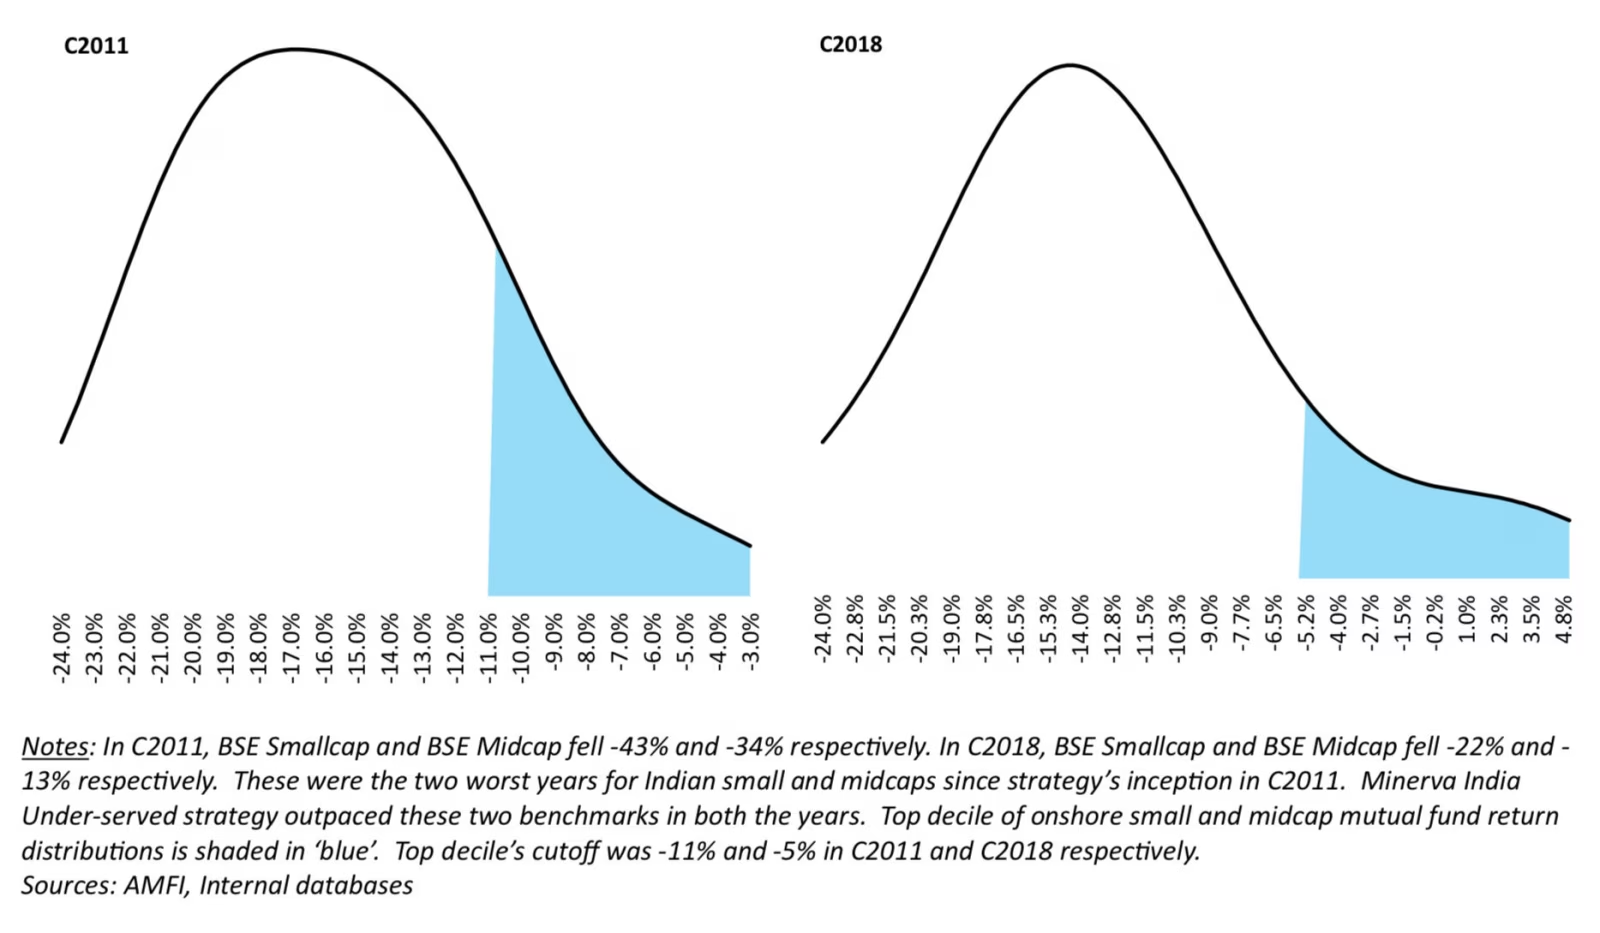
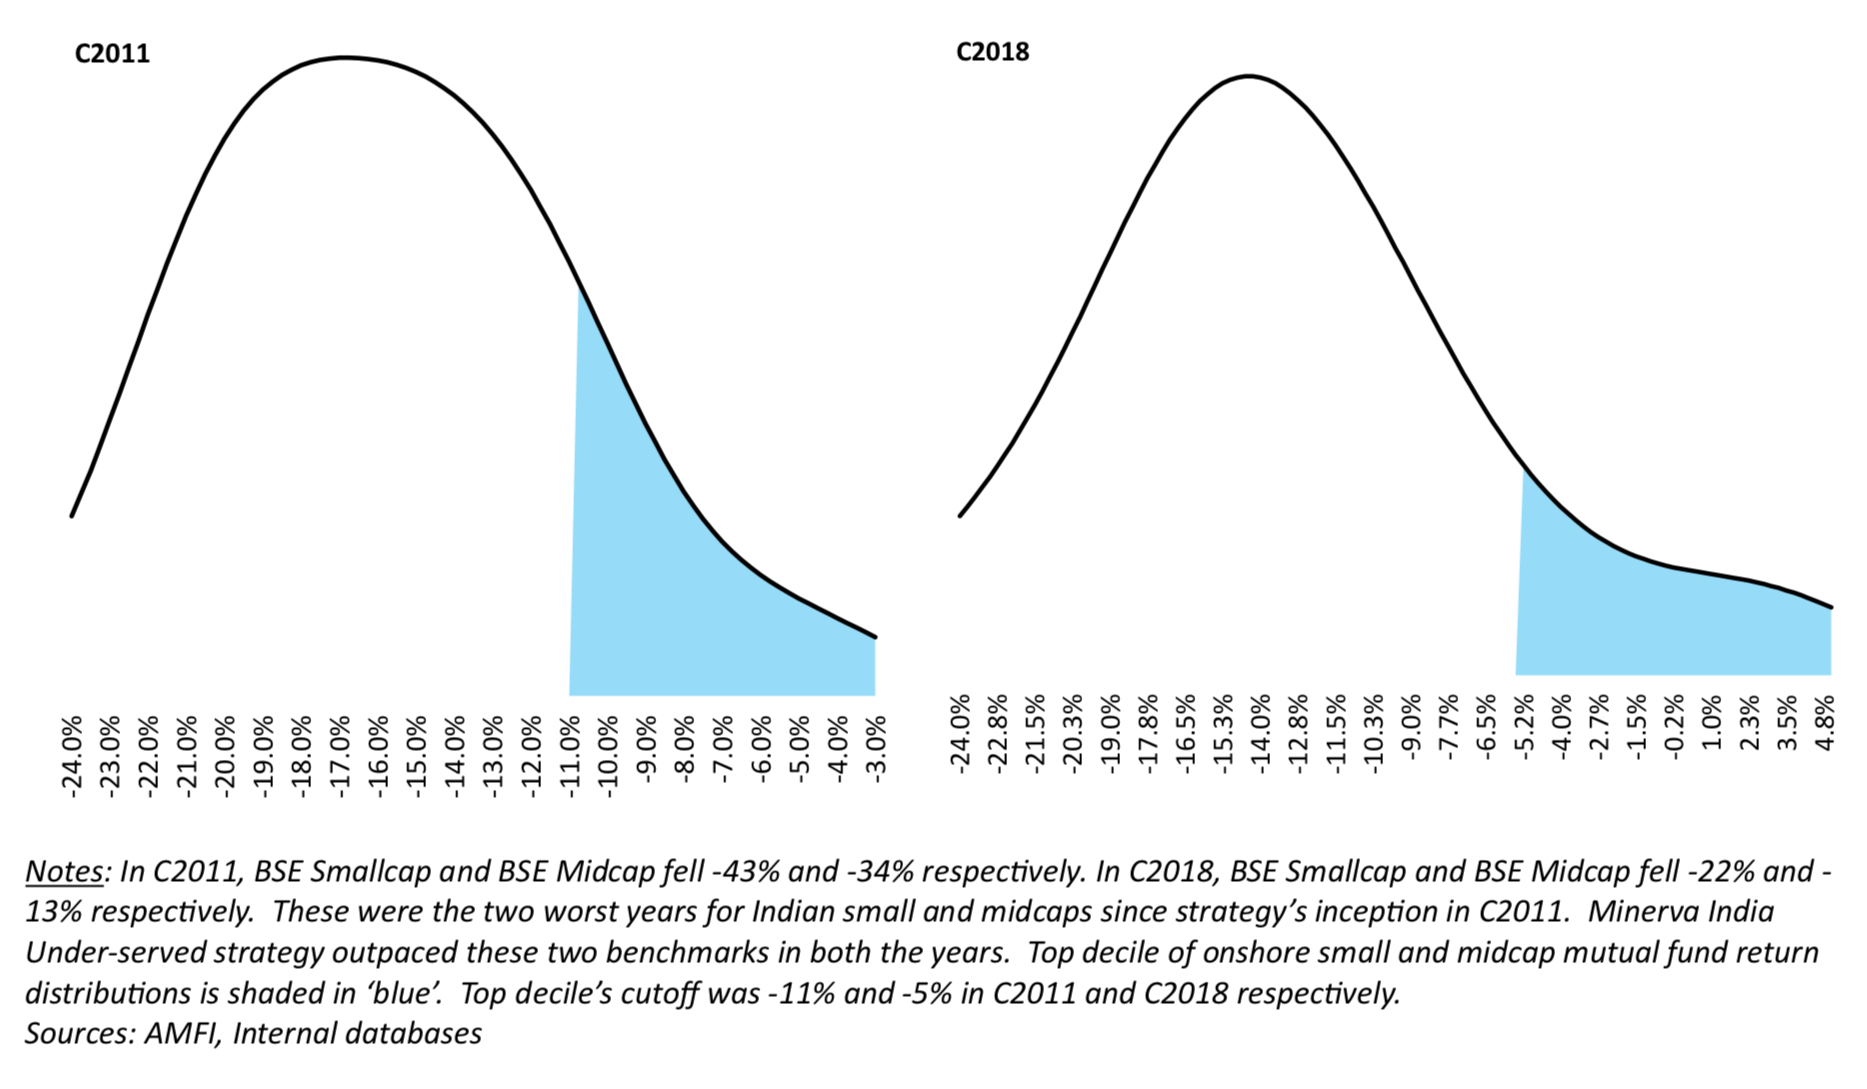
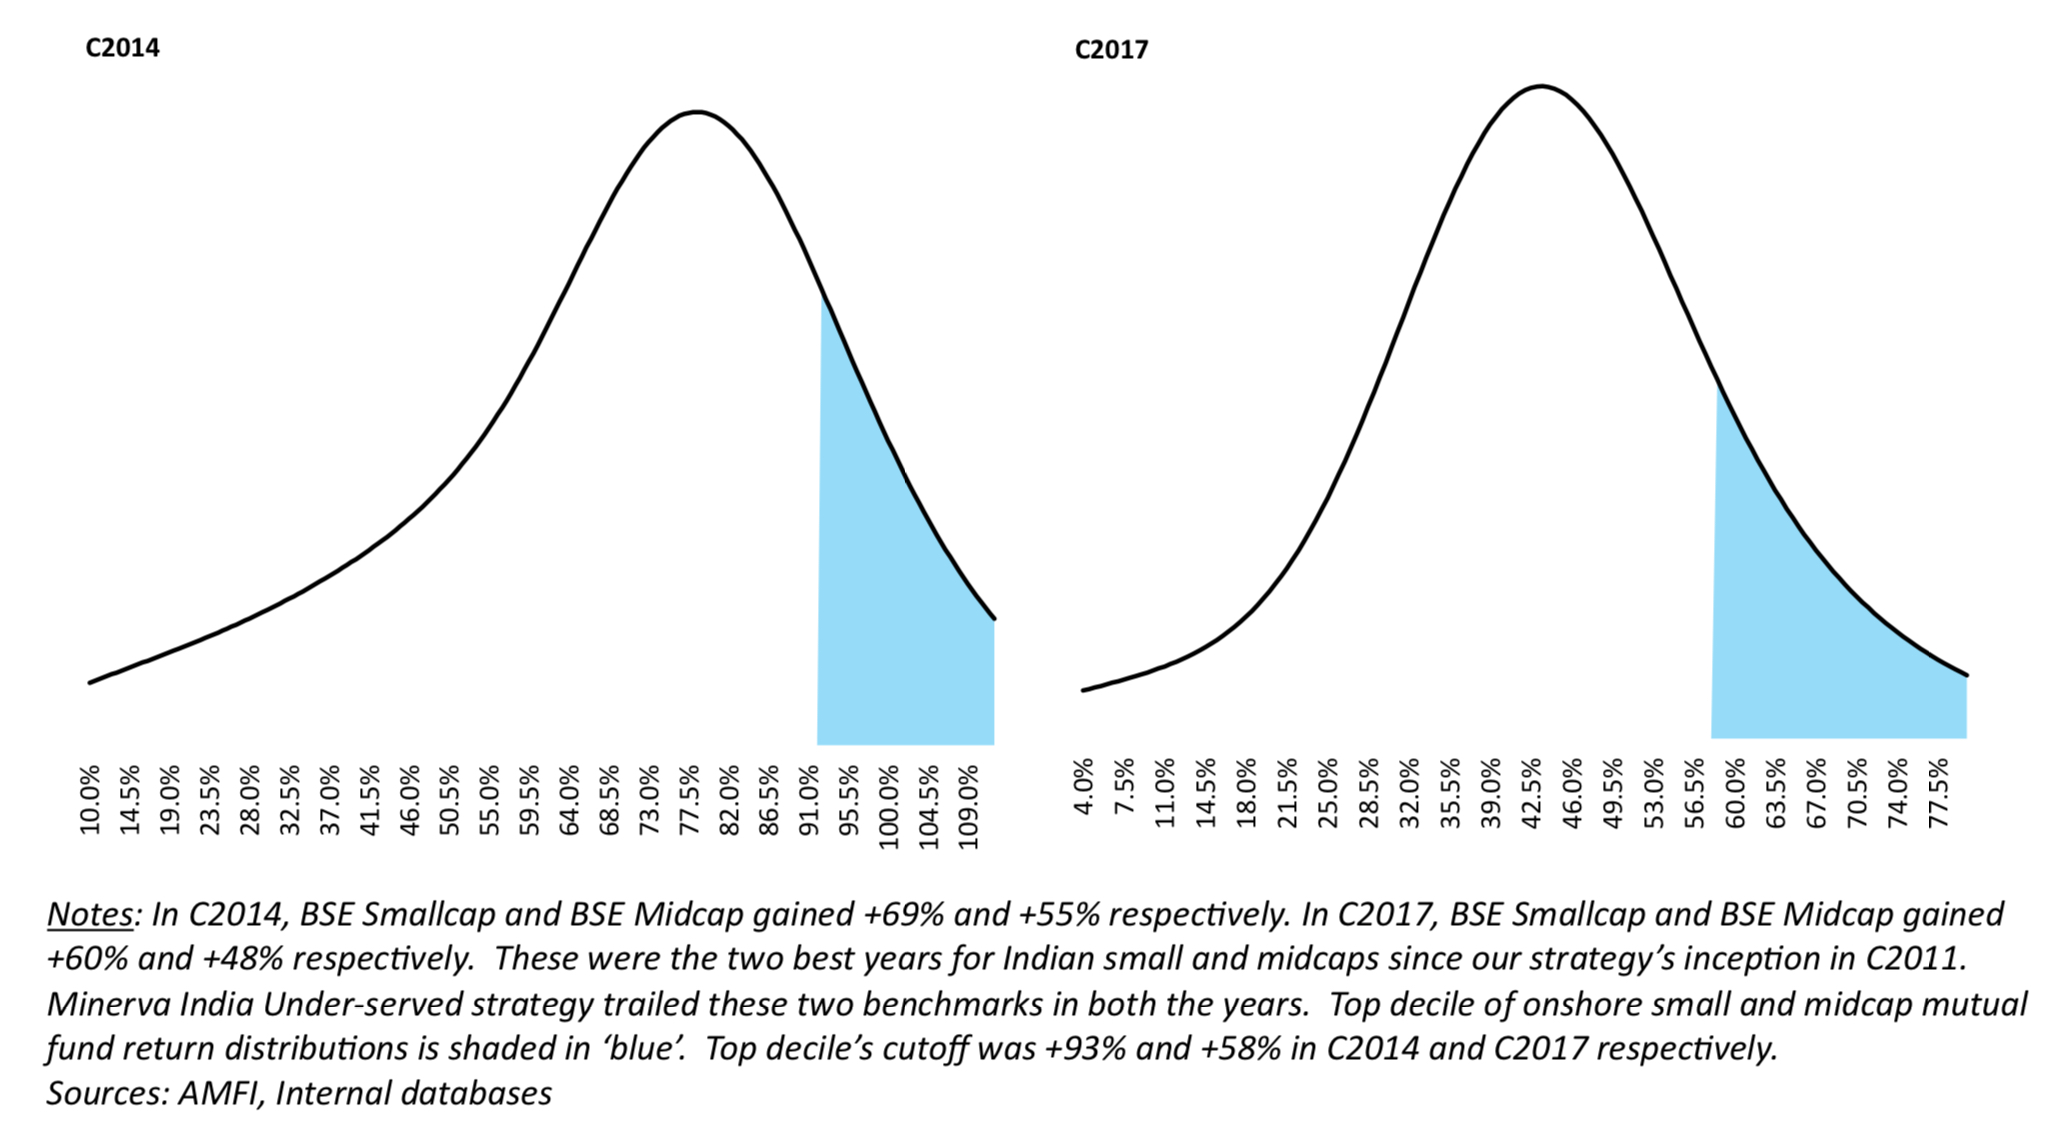
More often than not, significant outpacing in declining and flattish environments (C2011, C2018 etc.) comes with narrow leadership, suggesting that underlying performance of the high-hitters wasn’t driven by a popular theme or another popular factor (and therefore exhibits more durability). Consequently, the top-decile performers in such environments are materially departed from the median. Why is this important? Consider environments when ticker tape runs up indiscriminately – Close hugging with the crowd in such environments (i.e. when top decile performers aren’t as far vs. median performers) is often followed by fatigue (marginal buyer gets exhausted), and this can often coincide with increasing admission that prices are significantly disconnected vs. underlying operating returns and/or growth. In such set-ups, de-rating isn’t a risk; It’s usually the base case.
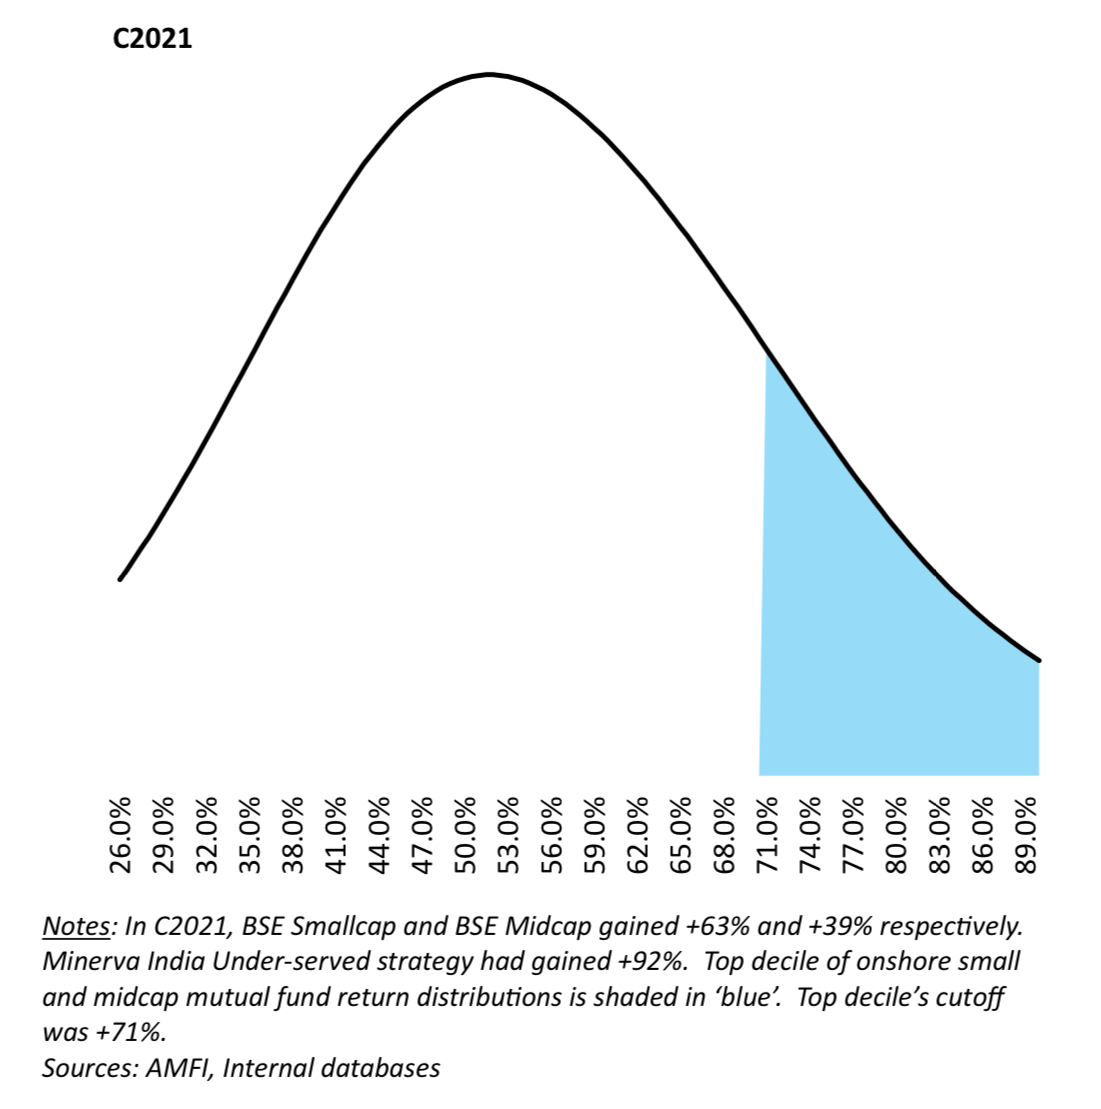
Attached exhibits lay down 3 return distribution sets for Indian mid and smallcap mutual funds – 2 biggest decline years since 2010, 2 biggest up years since 2010, and somewhat of an outlier year. Distributions confirm that large down-years (C2011 and C2018) show a ‘left skewed’ profile i.e. is less suggestive of group-think. In contrast, large up-years (C2014 and C2017) show ‘normal’ or ‘right skewed’ profiles (reflecting concentrated thematic euphoria – ‘Modi trade’ of domestic cyclicals in 2014, and Financials in 2017). As mentioned earlier, C2021 was an apparent outlier i.e. return distribution of Indian small and midcap mutual funds was ‘left skewed’ despite it being an otherwise solidly positive year.
DISCLAIMER: Investments in securities are subject to market risks. Read all the related documents carefully before investing. The information contained herein is believed to be reliable and has been obtained from sources believed to be reliable, but we make no representation or warranty, either expressed or implied, as to the accuracy, completeness or reliability of such information. We do not undertake, and have no duty, to advise you as to any information that comes to our attention after the date of this note or any changes in its opinion, estimates or projections. Prices and availability of securities are also subject to change without notice. This is not a prospectus and does not constitute investment advice or an offer or solicitation to buy or sell any designated investments discussed herein. Neither Minerva Asset Advisors, nor its officers, directors, agents, or employees make any warranty, express or implied, as to the suitability of any fund as an investment or of any kind whatsoever, or assumes any responsibility for, and none of these parties shall be liable for, any losses, damages, costs, or expenses, of any kind or description, arising out of this note or your investment in any fund. You understand that you are solely responsible for reviewing any fund, its offering and any statements made by a fund or its manager and for performing such due diligence as you may deem appropriate, including consulting your own legal and tax advisers. Minerva Asset Advisors | SEBI Registered Investment Adviser: INA000020332. Minerva India Under-served Fund LEI - 549300BQY3OUZWXLDZ68.